What the I-645 School-Funding Warning Leaves Out
The ballot says I-645 would decrease funding for schools, universities, and healthcare. It doesn't say when the money would arrive, or what the decrease is measured against.

Updates and analysis on Washington ESSB 6346 and its impact on startups and investors.
The ballot says I-645 would decrease funding for schools, universities, and healthcare. It doesn't say when the money would arrive, or what the decrease is measured against.
Washington can make its tax system fairer without accepting every argument for an income tax. A falling spending-to-income ratio is not a needs assessment, and more revenue is not a substitute for budget discipline.
Washington's new income tax has no prior-year estimated-tax safe harbor for first-time filers. A founder or early employee in an exit year can pay the entire tax with a timely filed return and still face a penalty.
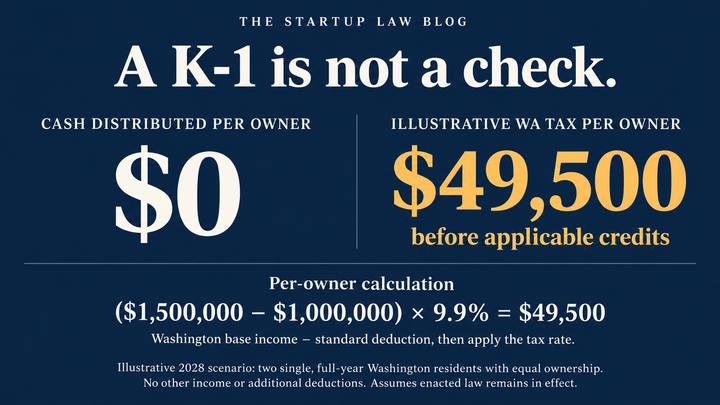
A K-1 is not a check. Starting with 2028 income, Washington’s 9.9% tax can reach profits owners never receive in cash. Here is the two-owner example.
If you own an S corporation or an LLC taxed as a partnership, your cash distributions don’t determine your tax bill. Retaining profits in the business can leave you with a personal tax obligation—and less cash to pay it.
Washington's estimate rose from 21,000 households to 25,000. The revision highlights a planning risk: the $1 million deduction may not keep pace with inflation. Sections 314 and 316 explain why—and leave an indexing question unresolved.
How Washington’s capital gains tax and 2028 income tax interact: when gains are added back, how the credit works, and examples using stated deduction assumptions.
IP26-645 expressly repeals the new income tax. Its broader prohibition raises a separate question about Washington’s capital gains tax.
Let's Go Washington reported 511,408 submitted signatures on July 2; the Secretary of State counted 509,365 petition lines and certified Initiative 645 by sample (12,936 of 15,281). What repeal would change — and why founders should keep planning as if the 9.9% tax takes effect.
Washington's 30-day safe harbor makes you a nonresident — it doesn't change your domicile. Long-term stock gains are allocated by domicile at the time of sale, so the safe harbor alone won't protect your exit.