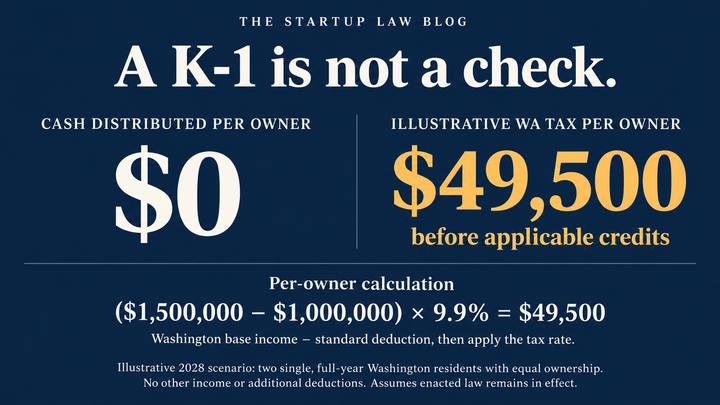
Washington's new personal income tax (ESSB 6346) imposes a 9.9% tax on income above a $1 million standard deduction. The deduction is $1 million per individual — except that spouses and registered domestic partners share one $1 million between them, whether they file jointly or separately. Not two. One per couple. For married filers, that single structural choice builds a meaningful marriage penalty into the Washington income tax that is scheduled to begin in 2028.
This post explains how the marriage penalty works, why it exists in this form, and what planning options exist for couples who will be hit by it.
The math, in one example
Consider two full-year Washington residents, each earning $700,000 of W-2 income. Assume the initial $1 million standard deduction and no other income, adjustments, deductions, or credits. Under ESSB 6346:
- If they are unmarried and each files individually: Neither clears the $1M threshold on their own. Combined state income tax: $0.
- If they are married and file jointly: Combined AGI of $1.4M against one $1 million deduction. Taxable amount: $400K (the excess over $1M). State income tax: $39,600.
- If they are married and file separately: The statute answers this directly: spouses share a single $1 million deduction regardless of filing status, so filing separately does not double the threshold. How the shared deduction is allocated between two separate returns awaits DOR guidance, but the combined result is the same: approximately $39,600, split between the two returns.
The penalty on this representative couple is $39,600 for a year under these assumptions. Repeating that amount for 15 years would total $594,000, but that illustration assumes unchanged income, law, deduction amounts, and other adjustments; it is not a forecast.
Why ESSB 6346 was structured this way
Section 314 expressly provides one deduction per couple. Two possible policy considerations help explain the structure, although they are inferences rather than documented legislative motives:
- Revenue. A per-filer $1M threshold would have exempted a meaningful number of high-earning dual-income couples. Revenue projections would have dropped.
- Simplicity. A single deduction per married couple mirrors federal AGI reporting conventions for joint filers, avoiding the need for a separate Washington filing status regime.
Whatever the policy rationale, the shared deduction is explicit in the enacted text. Filing separate Washington returns does not create a second deduction.
How big does the penalty get?
The penalty scales with how close the couple's combined income is to $1M and how concentrated the income is between spouses. A few representative cases:
- $600K + $600K = $1.2M combined: Taxable excess $200K. Tax: $19,800. Unmarried combined tax: $0. Marriage penalty: $19,800/year.
- $700K + $700K = $1.4M combined: Taxable excess $400K. Tax: $39,600. Unmarried combined tax: $0. Marriage penalty: $39,600/year.
- $900K + $900K = $1.8M combined: Taxable excess $800K. Tax: $79,200. Unmarried combined tax: $0. Marriage penalty: $79,200/year.
- $1.5M + $0 (single-earner couple): Taxable excess $500K. Tax: $49,500. Unmarried combined tax: $49,500 (the earner would hit $500K over the $1M solo threshold). Marriage penalty: $0.
Holding other adjustments constant, the shared-deduction penalty reaches its initial $99,000 maximum when each spouse has at least $1 million of income before the standard deduction. Equal earnings are not required. It is zero when one spouse earns all the income and the other earns nothing; a lower-earning spouse can still create a substantial penalty.
The year-to-year volatility problem
For couples whose income is roughly stable from year to year, the penalty is predictable and chronic. But a larger set of Washington couples — founders, investors, equity-compensated executives — have a different problem: episodic high-income years.
A founder couple with modest cash comp plus a large RSU vest in 2028 might see the couple's combined AGI spike to $5M in a single year before returning to $600K the next. In that spike year, the earning spouse clears the $1M deduction alone, married or not. The question is whether the $1M deduction applies per spouse or once per couple when the non-earning spouse contributes very little.
A large income spike does not automatically create a large marriage penalty. At the initial $1 million deduction and 9.9% rate, the penalty attributable solely to sharing the standard deduction cannot exceed $99,000 annually. It reaches that maximum when each person has at least $1 million of income before the standard deduction, holding other adjustments constant. If one person earns everything and the other earns nothing, this deduction-based penalty is zero. Other deductions, credits, and capital-gains interactions require separate analysis.
Planning responses
Planning cannot give a married couple two standard deductions under the enacted law. It can, however, reduce or eliminate tax liability by changing taxable income, available deductions or credits, or residency:
1. Time major recognitions around the marriage
For engaged couples, the relevant distinction is generally the tax year, not whether a sale closes before the ceremony. Federal filing status generally depends on marital status on the last day of the tax year. A sale before a wedding in the same calendar year therefore does not preserve unmarried filing status. Washington follows federal filing status under section 703, and section 314 gives spouses one shared deduction even on separate returns. Model any transaction across tax years with counsel before relying on a timing strategy.
For the initial $1 million standard deduction, the annual marriage penalty attributable solely to sharing that deduction is capped at $99,000. Actual savings depend on both partners’ income, residency, deductions, and credits; transaction timing alone does not establish the result.
2 — Income shifting does not reduce the combined tax
Simply reallocating income between spouses does not reduce their combined Washington income tax when their combined Washington income remains unchanged. Under ESSB 6346, section 314, spouses share one $1 million standard deduction whether they file jointly or separately. For example, shifting income from $1.1 million for one spouse and $100,000 for the other to $600,000 each leaves combined income at $1.2 million. Assuming full-year Washington residency and no other adjustments or credits, the initial $1 million deduction leaves $200,000 taxable at 9.9%: $19,800 either way. A tax reduction requires a change in the applicable income, deductions, or credits; shifting income to the lower-earning spouse alone does not accomplish that.
3. Maximize retirement deferral
Eligible pretax salary deferrals and deductible retirement-plan contributions can reduce federal AGI, the starting point for Washington’s tax. Roth contributions and nondeductible contributions do not provide that reduction. Contribution limits, plan terms, and eligibility matter. Taxable distributions generally enter income later, so evaluate deferral alongside expected future income and residency.
4. Front-load charitable giving
Federal itemized charitable deductions generally do not reduce AGI. Donating appreciated assets before a sale becomes binding may avoid realizing gain, subject to assignment-of-income and other rules. Separately, section 309 allows a Washington deduction for qualifying charitable contributions, capped at $100,000 and shared by spouses or registered domestic partners. Confirm the recipient and contribution meet the state requirements; a donor-advised-fund contribution is not automatically eligible.
5. Use non-grantor trusts for a portion of family investment income
A properly structured non-grantor trust may change who recognizes investment income, but out-of-state situs alone does not establish a Washington tax benefit. Review tax ownership, completed-gift status, trust residency and source income, and distributions to beneficiaries. Section 307 adds income of certain incomplete-gift non-grantor trusts back to the transferor’s income. See Trust Planning for Washington High Earners.
6. Change domicile
A genuine change of domicile and residency can reduce Washington income-tax exposure. Moving does not automatically eliminate the tax: Washington-source income may remain taxable, and part-year residency affects the calculation. Compare the complete facts and the destination state’s taxes before projecting savings. See How to Leave Washington.
Will the legislature fix this?
The legislature could change the shared deduction, but the enacted statute provides one deduction per couple. A larger deduction would generally reduce revenue relative to the current design; the amount would require a fiscal estimate. There is no basis here to assume that a legislative change will occur before the tax begins.
Plan using the enacted rule, while monitoring legislation, litigation, and Department of Revenue guidance.
Takeaways
- Washington's new personal income tax creates a real marriage penalty because the $1M deduction is shared by spouses, not doubled.
- The initial shared-deduction penalty is capped at $99,000 per year and reaches that cap when each person has at least $1 million of income before the deduction, holding other adjustments constant.
- A single-earner couple at the same total income pays the same tax either way; marriage is not penalizing.
- Planning may reduce or eliminate liability, but spouses cannot obtain two standard deductions simply by filing separately.
- A genuine change of residency can reduce exposure, but Washington-source income and part-year rules may leave Washington tax due.
For the full picture of ESSB 6346, see the Complete Guide. For relocation: How to Leave Washington.
Last reviewed: September 10, 2026. Nothing in this article is legal or tax advice. Consult the enacted statute and current Department of Revenue guidance when preparing returns or implementing a plan.