A genuine move out of Washington can change the tax treatment of a founder’s stock sale. A new mailing address alone cannot. Plan around three separate questions: where you are domiciled, whether you remain a statutory resident, and whether the income has a Washington source.
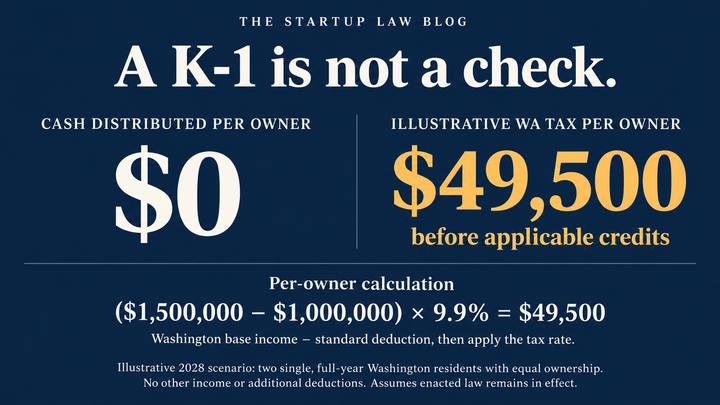
Under the enacted ESSB 6346, the income tax begins January 1, 2028, at 9.9% of Washington taxable income after applicable modifications and deductions. The initial standard deduction is $1 million, shared by spouses or state-registered domestic partners regardless of filing status. Washington’s existing capital gains tax requires a separate calculation.
This guide explains relocation planning under the enacted law. For developments that could change that framework, use the I-645 tracker and constitutional analysis. For an overview of an exit, see the Founder Exit Map.
Domicile: establish a new permanent home
You can maintain several residences but have only one domicile. Under Washington’s capital gains rule, an established domicile is presumed to continue. Changing it requires physical presence in the new location and an intention to make that location your permanent home. If your established domicile is Washington, you bear the burden of proving the change. See WAC 458-20-301(2)(c) and (6)(c).
Leaving Washington without establishing a new domicile does not complete the change. Retaining Washington property or family connections does not automatically prevent it, either. Your actual living arrangements and conduct must support the claimed new home.
There is no automatic six- or twelve-month waiting period. Starting early gives you time to complete a real move and document it. A short interval requires clear evidence; a long interval does not cure a move that exists only on paper.
Stock sales around a move
For personally held stock and other intangible property, Washington’s capital gains allocation rule looks to domicile when the sale or exchange occurs. A sale while domiciled in Washington is allocated here even if you move afterward. A sale after you have genuinely established domicile elsewhere is not allocated here under the intangible-property rule. The same timing principle applies when moving into Washington. Establish the change before the legally relevant sale or exchange; do not assume the cash-payment date controls. Allocation does not itself determine the tax due: exclusions, deductions, losses and credits still matter. See RCW 82.87.100(1)(b).
Deferred payments and later transactions
Separate the sale date from the year gain is recognized. For installment gain from an earlier stock sale, receiving payments after a move does not change domicile at the original sale. A later, separate sale of rollover equity requires analysis of domicile when that later sale occurs. Earnouts require classification under the transaction documents and applicable tax rules: deferred purchase price and compensation can have different treatment. Review each payment stream separately.
What Washington examines
The capital gains rule lists nonexclusive factors, weighed according to the circumstances. Build a consistent record of:
- Home and time: where you actually live, travel, and keep property. A home’s size or price is not a mathematical domicile test.
- Family: your spouse’s living arrangements and children’s schools. The rule presumes spouses or registered domestic partners share a domicile; different domiciles require support in the facts.
- Work and finances: where you work, conduct business and financial transactions, and maintain accounts.
- Official records: tax-return residence addresses, licensing, vehicle and voter registration, mailing addresses, and residence-based benefits.
A family member remaining in Washington is significant, but it does not automatically decide your domicile. Document the reason, duration, and actual arrangements. Different domiciles also do not automatically create two income-tax standard deductions; review the married-couple rules and community-property treatment together.
Build one timeline before you model the tax
Bring the following dates and documents to your first planning meeting. Label estimates as estimates and update the timeline when the transaction changes.
| Event | Date or expected date | Supporting record |
|---|---|---|
| Begin living in the destination home | ______ | Lease or closing documents; actual occupancy records |
| Change in use of the Washington home | ______ | Sale, rental, or continued-use records |
| Sign transaction documents | ______ | Signed agreement and amendments |
| Sale or exchange occurs | ______ | Closing documents; adviser analysis of the relevant tax date |
| Receive initial and deferred payments | ______ | Closing statement, installment schedule, or earnout terms |
| Work or spend time in Washington | ______ | Location log and workday records |
Ask your advisers to identify which date controls each tax question. A signing date, payment date, and legally relevant sale date need not be the same. The domicile change checklist helps organize the supporting records.
Plan and document the move
1. Choose a place you will actually live
Consider family, work, housing, and the destination’s overall tax and legal rules. A state’s lack of a broad personal income tax does not settle every planning question. The destination comparison provides a starting point for that discussion.
2. Establish the new home
Arrange housing and begin living there. Keep evidence of possession, moving dates, utilities, and actual occupancy. If you retain a Washington home, document its continuing use and availability. Ownership alone does not decide domicile, but retaining an abode can separately affect income-tax residency, especially in the move year.
3. Update records to match reality
Use the Washington Domicile Change Checklist for practical steps and supporting records. Meet the destination’s applicable licensing and registration deadlines. Claim residence-based benefits only when eligible. Update personal addresses without misrepresenting the company’s actual offices or operations; your personal move does not automatically relocate the business.
4. Keep a contemporaneous location log
Record Washington travel and visits, including flight, lodging, and transaction support where available. For the income-tax residency tests, any portion of a Washington calendar day counts.
Residency and the move-year problem
Do not treat the domicile-change date as the automatic end of every Washington tax exposure. The income tax has its own resident definition and part-year rules. Under ESSB 6346 §§101(8), 315 and 406:
- A Washington domiciliary generally qualifies as a resident. The exception requires all three conditions for the taxable year: no permanent Washington abode throughout the year, a permanent abode elsewhere throughout the year, and no more than 30 Washington days.
- Someone not domiciled in Washington during the year can qualify through maintaining a Washington abode and spending more than 183 days here. Staying below that threshold does not establish that your domicile changed.
- A part-year resident generally includes all adjusted gross income from the resident portion and Washington-source income from the nonresident portion, subject to statutory modifications. Pass-through items have a separate day-ratio rule under §406(2).
- The standard deduction for someone who is not a resident for the entire year is adjusted using Washington base income divided by federal adjusted gross income from all sources, capped at one. It is not simply prorated by months.
Keeping a Washington abode raises a specific move-year issue. Section 101(8)(c) applies after an individual qualifies as a resident under subsection (a), and describes the resident portion by reference to domicile or maintaining a Washington abode. For someone domiciled here during the move year, that text creates a risk that keeping an abode extends the resident portion beyond the domicile change. This is an interpretive risk to resolve before relying on a midyear departure, rather than a settled conclusion about every retained home.
In a later year with no Washington domicile at any time, an abode alone does not satisfy the non-domiciliary test: more than 183 Washington days are also required. Conversely, the domiciliary’s 30-day exception changes income-tax resident status, not domicile for the stock-sale capital gains allocation rule. See the 30-day rule explained.
Washington-source income can remain
Beginning in 2028, a nonresident may still owe income tax on compensation for Washington work and income allocated or apportioned here from a business or pass-through entity. The employer’s address alone does not determine where employment income is sourced. Apply the relevant rules and exceptions to the actual work and income involved. ESSB 6346 §§401–407.
Classify sale proceeds, equity compensation, short-term gains, and other receipts separately. A domicile change relevant to a personally held stock sale does not answer the sourcing of compensation or an entity’s business income. Review the founder’s planning guide alongside your transaction documents.
Example: A founder genuinely establishes Nevada domicile in June 2028, keeps a Washington home available, and returns for 20 workdays later that year. A later sale of personally held stock producing long-term capital gain is not allocated to Washington under the capital gains domicile rule. Retaining the Washington home may affect move-year income-tax residency—an interpretive risk, not a settled conclusion—but resident status does not automatically bring that federal long-term gain into the Washington income-tax base. Under ESSB 6346 §302, federal long-term capital gains and losses are removed from Washington base income, and a taxpayer who owes Washington capital gains tax for the year adds back Washington capital gains (plus the amount deducted under RCW 82.87.060(1)), excluding gains and losses from sales or exchanges exempt under RCW 82.87.050. Compensation for the Washington workdays and continuing business or pass-through income remain separate questions. The move, the home, and the work answer different tax questions; the applicable deductions and credits still determine whether tax is due.
Calculate the two taxes separately
Beginning in 2028, calculate Washington’s capital gains tax and income tax separately, then apply the available credits. Section 205 allows a nonrefundable income-tax credit for the same year’s Washington capital gains tax, limited to the income tax otherwise owed. Ignoring other credits, combined liability is the greater of the two separately calculated taxes. The income-tax deduction applies once to the combined income-tax base, not separately to wages and gains. For the gain adjustments and worked examples, see the full tax-coordination explanation.
Preserve the evidence
Keep a single file with the move timeline, housing and occupancy records, location log, registrations, address updates, tax filings, and explanations of any continuing Washington ties—including facts that complicate the analysis.
Preserve records through applicable assessment periods and while they remain relevant to later years. Section 702(8) generally measures the income-tax assessment limit from the year a return is filed, with exceptions. Federal changes, missing returns, and other exceptions require separate analysis before discarding records; a universal seven-year instruction does not resolve every case.
If moving is not practical
Model the actual transaction and household income before making major changes. Review income timing, available exclusions such as QSBS, and any proposed trust or ownership structure on their own terms. None substitutes automatically for a genuine domicile change. Washington does not impose a deemed market-value sale merely because you leave; that does not eliminate tax on actual transactions or continuing Washington-source income.
Credits and filing
If another jurisdiction also taxes the gain, review the limited credit under RCW 82.87.100(2) and WAC 458-20-301(6)(d). It requires qualifying tax actually paid and is capped at the Washington tax on the same qualifying gains; unused credit is not refundable or carried forward or back.
For Washington capital gains return, extension, and payment mechanics, see the Washington capital gains tax guide.
How we can help
For help reviewing your move, transaction timing, and continuing Washington connections, book a 20-minute call with Joe Wallin or email wallin@carneylaw.com.
Last revised: September 18, 2026. This article is for general educational purposes and does not constitute legal or tax advice.