What to Put on Your Section 351 Statement When Nobody Knows What the Company Is Worth
How not to screw up your 10x basis, which could be worth far more than the $15 million cap.

Tax planning strategies for startup founders, investors, and employees, including QSBS and equity compensation.
How not to screw up your 10x basis, which could be worth far more than the $15 million cap.
Washington's new income tax has no prior-year estimated-tax safe harbor for first-time filers. A founder or early employee in an exit year can pay the entire tax with a timely filed return and still face a penalty.
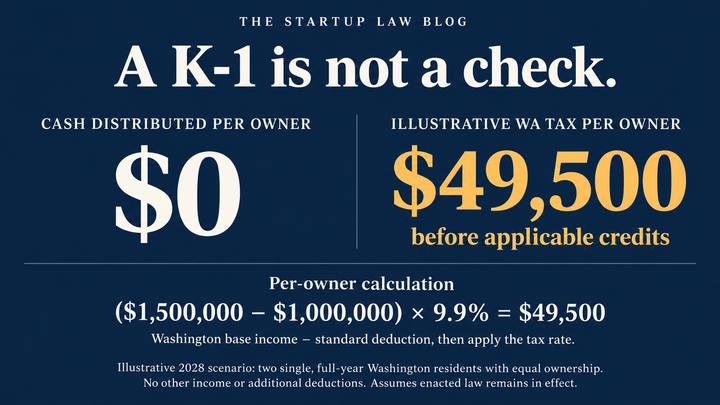
A K-1 is not a check. Starting with 2028 income, Washington’s 9.9% tax can reach profits owners never receive in cash. Here is the two-owner example.
S corporation stock is not QSBS. But an S corporation may hold qualifying stock in a new C-corporation subsidiary. Here is how the strategy works—and where it can fail.
If you own an S corporation or an LLC taxed as a partnership, your cash distributions don’t determine your tax bill. Retaining profits in the business can leave you with a personal tax obligation—and less cash to pay it.
How the first-six-month test, working-capital rules and company-age cap affect Section 1045 replacement stock, with examples of cash and active-asset valuation.
IP26-645 expressly repeals the new income tax. Its broader prohibition raises a separate question about Washington’s capital gains tax.
In a stock-for-stock acquisition, your QSBS may survive under Section 1202(h)(4) — but with an exchange-date gain cap most shareholders don't know about.
Initiative 645 is certified for the November 3, 2026 ballot — but the 9.9% tax remains law, effective January 1, 2028. The planning playbook for Washington founders, investors, and high earners.
Separate the QSBS gross-assets test, contributed-property FMV rules, shareholder basis and eligible-gain limit—with a worked example of pre-contribution appreciation.