Roth Conversions and Washington's 2028 Income Tax
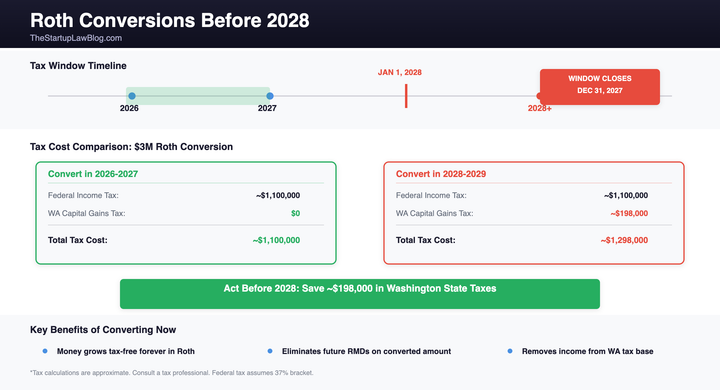
Roth conversions do not end in 2028. Washington’s tax depends on the taxable conversion plus other income, available deductions, and the timing of each year’s income.

Page 5
Roth conversions do not end in 2028. Washington’s tax depends on the taxable conversion plus other income, available deductions, and the timing of each year’s income.
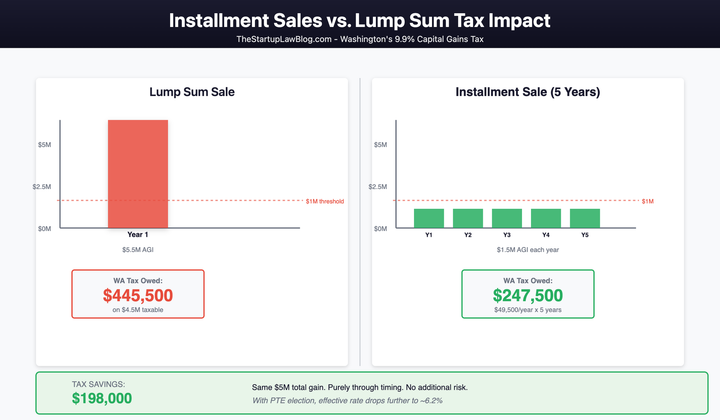
Installment sales can spread eligible gain, but Washington’s two tax bases, sale-date allocation, credits and financing risks determine the result.
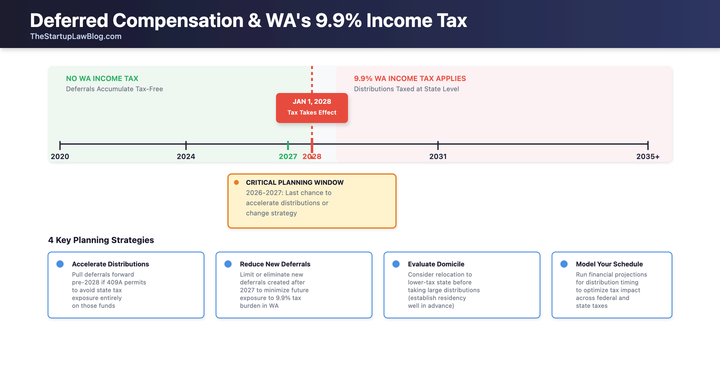
Compensation earned before 2028 under an NQDC plan can enter Washington's 9.9% income-tax calculation when included federally in 2028 or later — subject to residency, sourcing, §409A payment rules, and 4 U.S.C. §114.
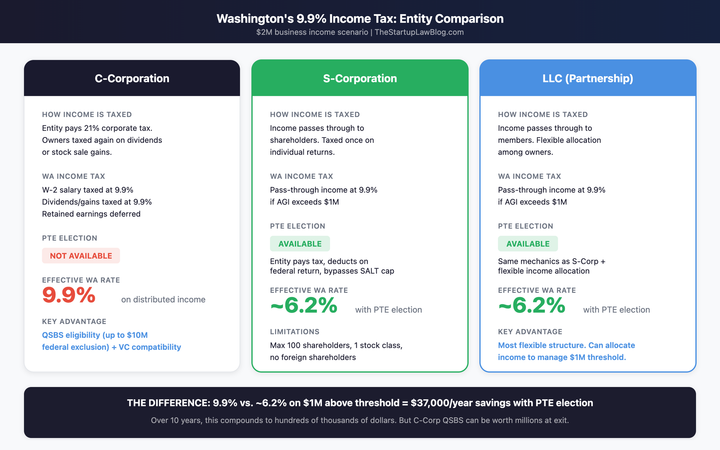
Washington’s new income tax adds another consideration when choosing a business structure. Compare the combined federal and state taxes, how much profit you expect to distribute, and how you expect to sell the business before changing entities.
Washington could raise its income tax, but increases are not inevitable. Compare state histories, the deduction’s indexing rules and practical planning scenarios.
Compare Washington, Oregon, and Nevada taxes on founder income, QSBS gains, businesses, and estates, with defined examples and relocation rules.
How Washington’s income tax affects estate planning: evaluate gifts, GRATs, ILITs and Roth conversions, with timing and tax consequences specific to each strategy.
Washington’s income tax begins in 2028. Estimated payments are not required before July 1, 2029. Understand the annual payment, 90%/100% penalty protection, and PTE rules.
Washington’s charitable deduction has a $100,000 cap shared by couples. DAF deductions, CRT distributions and QCD exclusions work differently; model both state taxes.
Washington’s 2028 income tax can reach taxable retirement distributions and Social Security. Learn how basis, Roth withdrawals, other income, and residency affect the calculation.