Opinion • October 3, 2026
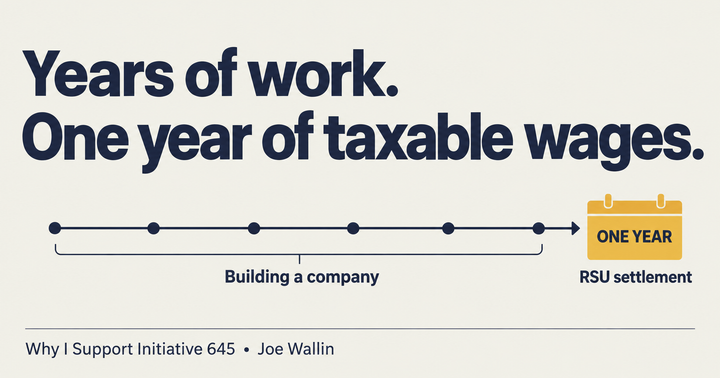
I support Initiative 645. The way a startup employee’s restricted stock units can turn years of work into one year of taxable wages is one reason why.
Imagine an employee who spends a decade helping build a company. The company goes public. Under the terms of this hypothetical award, the employee’s RSUs vest and settle in shares six months later, in 2028. Assume the employee lives and works in Washington throughout, and no special federal tax deferral applies.
The value delivered through that settlement is generally wage income. The employee does not have to sell the shares for that compensation to become taxable. A later sale is a separate tax event. The precise timing depends on the award’s terms; six months after an IPO is an example, not a universal rule.
Under Washington’s enacted income-tax law, the 9.9% tax begins January 1, 2028, with a $1 million standard deduction, shared by spouses and registered domestic partners. A large RSU settlement can push an employee above that annual deduction even if their usual annual compensation is far below it.
That is the concern behind my post today: years spent building a company can produce compensation recognized in a single tax year. One unusually large W-2 does not mean someone has been earning that amount every year.
I do not think an annual threshold adequately captures that distinction. That is one reason I support repealing the new income tax.
Vote YES on Initiative 645.
For the measure’s status, what repeal would do, and the related litigation, see my Initiative 645 Status & Litigation Tracker.
RSU tax background: IRS discussion of stock-settled awards and income timing. This example illustrates a timing issue; individual results depend on the award and the taxpayer’s circumstances.
Six months after the IPO, the RSUs vest. That isn't a stock sale. It's wages, all in one year.
— Joe Wallin (@joewallin) October 3, 2026
Washington doesn't tax the decade it took to earn them. It taxes the year they show up.
Vote YES on I-645.